Home Blog Page 7

Ghost Bites (AECI | Jubilee Metals | Lighthouse Properties | Merafe | Northam Platinum | Powerfleet | Sabvest)

In this edition of Ghost Bites:

  • The market didn’t like the AECI results
  • Jubilee Metals looks set to sell its Large Waste Project
  • Lighthouse shines in a great interim period
  • Merafe can thank chrome ore for saving the day
  • Records tumble at Northam Platinum
  • Powerfleet is still loss-making
  • Sabvest announces a bolt-on deal at ITL

The market didn’t like the AECI results (JSE: AFE)

Was it the free cash outflow that spooked investors?

AECI has reported results for the six months to June 2026. It wasn’t an easy time, with revenue from continuing operations down by 4%. Despite this, profit from continuing operations jumped by 20%!

By the time you reach the bottom of the income statement, you find HEPS growth of 8%. The interim dividend was even better, up by 16%.

The confidence to increase the dividend payout ratio was no doubt boosted by the decrease in net debt of roughly 40%. In absolute terms, net debt decreased by R1.2 billion, partially due to proceeds received from divestments.

And just to add to the confusing shape of this result, free cash moved from an inflow of R251 million in the prior period to an outflow of R952 million in this period. This was driven by a 19% increase in capital expenditure to R417 million, as well as as almost R600 million tied up in incremental working capital.

So, what actually happened here?

Looking at the segmentals, AECI Mining had an improved operational performance, with both revenue and EBITDA up by 6%. EBITDA margin held steady at 15%, driven by product mix and cost management. Both Asia Pacific and Southern Africa have been noted as highlights.

The AECI Chemicals business is hard to compare to the previous year due to disposals. If we just focus on this year, then the business could only manage an EBITDA margin of 7% – in line with the previous year. But below the EBITDA line, we find an impairment of R320 million due to the ongoing losses at Schirm.

AECI actually splits this segment in two, with “Chemicals Core” growing EBITDA by 14%, while “Schirm and other” fell by 70%. You can immediately spot the problem.

AECI Chemicals also ate up the free cash flow, with an outflow of R537 million for the period vs. a R661 million inflow in the comparable period. They attribute this to “strategic investment in working capital”.

The company expects improved free cash flow in the second half of the year. After the share price fell by nearly 10% in response to these numbers (and then dipped again the next day), management will need to tell a better cash flow story to get the share price back on track.

Ghost Bite: AECI has been fighting a tough battle for the past few years. Schirm is currently the major headache, serving as a good reminder that offshore isn’t always better.


Jubilee Metals looks set to sell its Large Waste Project (JSE: JBL)

This will free up capital for investment in other copper assets in Zambia

Jubilee Metals has announced the receipt of two binding offers for its Large Waste Project – and at a “substantial premium” to what they originally paid for it. They haven’t owned it for very long, as Jubilee still owes the final $5 million to the original seller of the asset!

This disposal would free up capital that Jubilee can then apply to its other projects in Zambia. One such example is the on-site copper processing facility at the expanded Molefe Mine operations. The original seller has thankfully agreed to be paid the $5 million in Jubilee shares, so that improves the situation even further in terms of Jubilee keeping cash available for other projects.

Together with the remaining proceeds of the exit of South African assets, Jubilee has indicated a war chest of nearly $100 million to play with. Be careful of the cash flow timing though – the disposal of the Large Waste Project would be structured as a deal with instalments of up to 3 years. It’s extremely rare to get paid everything up-front in these deals. In fact, that’s exactly why Jubilee still owes $5 million to the original seller of the asset!

To get the disposal of this asset across the line, Jubilee must now choose which of the two potential partners to dance with. The goal is to move quickly here, with definitive transaction agreements set to be concluded within the next two weeks.

Ghost Bite: Stretching a balance sheet and trying to take on too many projects isn’t a smart approach. I far prefer seeing sensible decisions like these.


Lighthouse shines in a great interim period (JSE: LTE)

This is a perfect example of why I invest in property stocks and ETFs on the JSE

Lighthouse Properties released results for the six months to June 2026. This property fund is focused on Western Europe – specifically Spain, Portugal and France. It’s a strategy that has been working beautifully, evidenced by growth that is well ahead of inflation in all three markets.

The group has achieved growth in distributable earnings per share of 9.7%. When the underlying exposure is hard currency markets, that’s really impressive.

The direct property portfolio grew net property income by 4.5% on a like-for-like basis. Despite the ongoing adoption of online shopping, footfall increased by 3.0%.

France led the way with 6.6% like-for-like growth, followed by Spain at 5.8% and Portugal at only 1.7%. Around 28.1% of the direct portfolio is found in Portugal (measured by fair value), so it would be good to see that number increase. It’s unfortunate that France is only 12.8% of the portfolio, as that has been the star performer.

The loan-to-value ratio sits at a health 35.9%, similar to 36% a year ago.

The full year guidance has been revised upwards to growth in distributable income per share of between 6.9% and 8.7%. It might be even better than that if they can keep up the performance seen in the first half!

Ghost Bite: This is one of many excellent property funds on the JSE.


Merafe can thank chrome ore for saving the day (JSE: MRF)

There’s more to this business than just the smelters

Merafe has added its name to the long list of company releasing results for the six months to June 2026. Despite the ferrochrome smelter sector being in disarray (with a 75% drop in ferrochrome production), Merafe still managed to somehow grow profit from R233 million to R512 million!

The heavy lifting was done by chrome ore sales volumes (up 75%), accompanied by better commodity prices. This drove a 36% increase in revenue and a 60% jump in EBITDA. HEPS was up by 64% to 20.7 cents.

Perhaps most importantly, cash from operating activities swung wildly from an outflow of R175 million to an inflow of R976 million. This would’ve given the board the confidence required to increase the interim dividend from 4 cents per share to 16 cents per share!

Of course, the outlook for the rest of the year is much better, as the special tariffs from Eskom have changed the game for the smelters. They do note the risks of market oversupply and cheap imports, but at least the smelters actually have a chance.

Ghost Bite: Those who took a risk on Merafe have been richly rewarded this year, with the share price up 35% year-to-date. Will the lifeline from Eskom be enough for the smelters in the second half of the year?


Records tumble at Northam Platinum (JSE: NPH)

They are looking to ramp up production in the coming years

Northam Platinum released a trading statement for the year ended June 2026. It’s incredibly detailed, so this is far more than just a standard trading statement.

Total equivalent refined PGM produced from own operations increased by 4.4% to a record level. Chrome concentrate also achieved a new record, up 17.4%. You’ll find the word “record” in a bunch of other places as well, all adding up to a wonderful 64.1% increase in sales revenue.

The biggest driver of this increase was a 57.4% jumped in the rand 4E basket price, along with an 8.0% improvement in total sales.

With unit cash costs per ounce only up by 6.4%, it was a bonanza by the time we reach operating profit. A 293.8% increase is a reminder of how lucrative things can be when mining goes well.

Here comes that word again: record HEPS of between R30.06 and R30.82. Compared to ~R3.81 in the prior period, that’s an incredible jump.

Notably, the board has changed the dividend policy as well. It used to be a minimum of 25% of headline earnings. In practice, the company has been paying around 42% of headline earnings out as a dividend, so they’ve now raised the policy to a minimum of 40%. It probably won’t have much of a practical effect, but it does set a new floor.

I’m quite sure that this change in policy is also designed to give investors comfort around “Vision 2031” – Northam’s plan to invest in existing operations to increase production. Alongside the push for production from owned mines, they also expect to double metal purchases from third parties over the next five years. The market will want to see a balance between capex and dividends, hence the new policy.

Northam goes so far as to describe this capex plan as “bullet-proofing” the business. It tells you how much things have improved in this sector that management teams are even willing to say something like that.

As part of supporting that plan, Northam also announced an increase in its revolving credit facility from R13.3 billion to R15.0 billion. This facility matures in August 2027, so they are probably thinking about the refinancing negotiations at this stage as well.

Ghost Bite: Despite the wild growth in earnings, the share price is only up 24% over 12 months (and down 20% year-to-date). The market is always nervous of the good times continuing in PGMs.


Powerfleet is still loss-making (JSE: PWR)

You may recall that this is the company that swallowed up MiX Telematics

Powerfleet’s financial reporting isn’t easy for South Africans to work with, as the company is listed in the US and reports based on the SEC format. They unfortunately don’t include the management commentary in the SENS announcement, so you have to go hunting for it.

The telematics group grew total revenue by 6.4%. There’s quite a change in mix though, as Services increased by 9.1% and Products fell by 6.7%. This is because product shipments were delayed for the quarter.

The change in mix was good for gross profit at least, which increased from 54.2% to 55.2%. As is usually the case, a services business model is more lucrative than selling products.

Selling, general and administrative expenses increased by 5.3%. That’s slower than revenue growth, which of course is very good for margins. A further boost came from the reduction in research and development costs by 10.2%.

Despite all the positive underlying momentum in the business, the net loss attribute to common stockholders was still $8.4 million. That’s an improvement on the net loss of $10.2 million, but it means that the company is still reporting significant losses.

Like all good US tech companies though, adjusted EBITDA has gone the right way – up from $20.1 million to $21.5 million. As usual, one of the important adjustments is stock-based compensation (effectively share awards to staff), which jumped from $1.8 million to $3.1 million. IFRS reporting doesn’t allow companies to pretend that this isn’t an expense.

Ghost Bite: There’s not much trade in this stock, but it’s certainly been a volatile year with a 52-week low of R44.01 and a 52-week high of R100.00! The current price is R65.00.


Sabvest announces a bolt-on deal at ITL (JSE: SBP)

This is a great example of how the group executes its strategy

Sabvest is seen as the best of the local investment holding companies. Don’t just take my word for it – you can look at the Price/Book of 0.84x, or a discount of only 16% to the book value. Companies in this sector tend to trade at discounts of 40% or more!

The market supports the Sabvest story because of the underlying assets that are otherwise impossible to reach. Rather than being a collection of listed stakes, Sabvest has built an extensive portfolio of private companies. Sabvest can then support those companies with capital and networks to unlock growth.

One such example is ITL Group, an apparel labelling and supply chain management business in which Sabvest has a 34% stake. This is where the latest bolt-on deal is housed, with ITL set to acquire 100% of Rudholm Group International, a Swedish packaging and labelling company serving markets across Europe, Asia and North America.

It’s a part-cash, part-share deal that will see the current Rudholm shareholders take an 11% stake in the ITL-Rudholm group. This will dilute Sabvest’s stake down to 30.5%. The transaction is expected to be value-accretive to Sabvest shareholders.

A transaction value for the deal hasn’t been disclosed.

Ghost Bite: Bolt-on deals are almost always a better idea than swashbuckling M&A that bets the farm on one specific trade.


Nibbles:

  • Spear REIT (JSE: SEA) has concluded an agreement with Mambos Storage & Home to develop their distribution centre in Cape Town. Mambos has grown to 22 stores nationwide and clearly has plans to grow further. This will add to Spear’s existing industrial property portfolio in the Western Cape. It’s not always easy to find good properties to acquire, so being able to do projects like these is important for Spear’s ongoing growth. The development cost is estimated to be R90 million, with work commencing in August 2026 and expected to conclude in mid-2027.
  • There’s still almost no trade in Aimia’s (JSE: AII) shares on the JSE, so I’ll just give the results for the second quarter a passing mention down here. Aimia is cash flush after the disposal of Bozzetto, which generated $270m in net proceeds. They’ve been using this to get rid of debt (over $131m in senior notes) and repurchase around 10% of shares outstanding. A further share buyback programme is underway. The continuing operations (mainly Cortland International) saw revenue decline by 3.7% this quarter, while adjusted EBITDA fell by roughly 18%.
Ghost Bites (Advtech | Gold Fields | Italtile | MTN | Southern Palladium)

In this edition of Ghost Bites:

  • Advtech shows that school is still cool – for investors, at least
  • Gold Fields doubled free cash flow in the interim period
  • Italtile’s business remains under pressure
  • MTN’s share price takes another knock
  • Southern Palladium has been granted a mining right

Advtech shows that school is still cool – for investors, at least (JSE: ADH)

Mid-teens growth is the order of the day

Advtech is due to release results on 24 August. In the meantime, they’ve given the market a voluntary trading statement to chew on.

The reason why this is voluntary is because the percentage movement in earnings is lower than 20%. If it was higher, then they would be forced to release a trading statement under JSE rules. Instead, Advtech’s approach just reflects a commitment to keeping investors informed – something that a lot of listed companies could learn from.

Speaking of learning, the education-focused group is doing very well. For the six months to June, they grew HEPS by between 13% and 18%. Normalised earnings per share grew by a similar range.

Ghost Bite: It’s a solid growth rate, but is it enough to justify the 46% increase in the share price in the past 12 months? Or the P/E of 20x, for that matter? We will see what the share price does after full results are released.


Gold Fields doubled free cash flow in the interim period (JSE: GFI)

But keep an eye on the inflationary pressures

Gold Fields has released a trading statement dealing with the six months to June. With an increase in both gold production and the average gold price, you can already guess the direction of travel here.

But just how much money did they make? Well, HEPS is expected to be between 72% and 90% higher than the comparable period. That’s a lot!

It gets even better at adjusted free cash flow level, which is a measure of how value is actually flowing to shareholders. This metric is up by between 91% and 111%. At the mid-point, that means that adjusted free cash flow doubled year-on-year.

Management can’t control the gold price, but they can control production. It’s important to see that production for the second half of the year is expected to be in line with the first half. This is part of a broader expectation of meeting 2026 production guidance.

If you dig into specific mines, you’ll see more volatility in expected production – Salares Norte is running ahead of guidance, while Gruyere and Tarkwa are at risk of not meeting guidance.

The other thing to watch will be the cost of production, as there are inflationary and other pressures that have increased the burden associated with getting the stuff out of the ground. All-in sustaining cost per ounce was 13% higher over the six-month period. That’s quite a hurdle rate for the gold price to overcome.

Ghost Bite: Mining share prices move based on current commodity prices, not the earnings that happened months ago. That’s why Gold Fields is down 26% year-to-date despite indicating such strong growth.


Italtile’s business remains under pressure (JSE: ITE)

Management has been incredibly transparent with the market about the issues being faced

Full marks to Italtile – the management team has been committed to keeping the market appraised of the substantial challenges that the business is dealing with. I hope that Brandon Wood, the CEO as of 1 July 2026, will keep that going.

He certainly isn’t taking the top job at a company that is having an easy time of things. A voluntary trading statement for the year ended June shows that HEPS is expected to decrease by between 7.5% and 12.4%. Aside from the obvious stuff like a soft SA consumer environment, there’s the overcapacity in the tile manufacturing segment that is crushing margins in that space.

The problem with manufacturing is the extent of fixed costs and operating leverage. If you lose even a modest portion of sales, it has a significant impact on the bottom line. When weak demand is combined with the proliferation of cheap imports, local manufacturing has a bad time.

There’s at least some relief there, with the International Trade Administration Commission of South Africa (ITAC) announcing provisional anti-dumping duties on various tiles in July 2026. Let’s see how much difference they really make.

Looking at the retail side of the business, system-wide turnover reported by CTM, Italtile and TopT was stable against the prior period. Italtile Retail (the more upmarket offering) performed well, while CTM (more affordable products) was flat. To be fair, CTM’s flat performance was achieved despite the franchising of four company-owned stores, a process that would naturally give revenue a knock.

The webstores registered increased traffic and sales, so people are buying more stuff online – even in discretionary categories like tiles!

The integrated supply chain business saw sales decline by 6% in this retail environment, but they managed to get margins higher due to the exchange rate and improved buying.

Then we get to the problematic manufacturing business, where sales were down by 1%. That may not sound terrible, but Italtile describes margins as being under “severe pressure” from market pricing and energy-related costs.

On the plus side, Italtile’s cash flow story remains strong despite the obvious underlying pressures.

Full details will be available on 24 August.

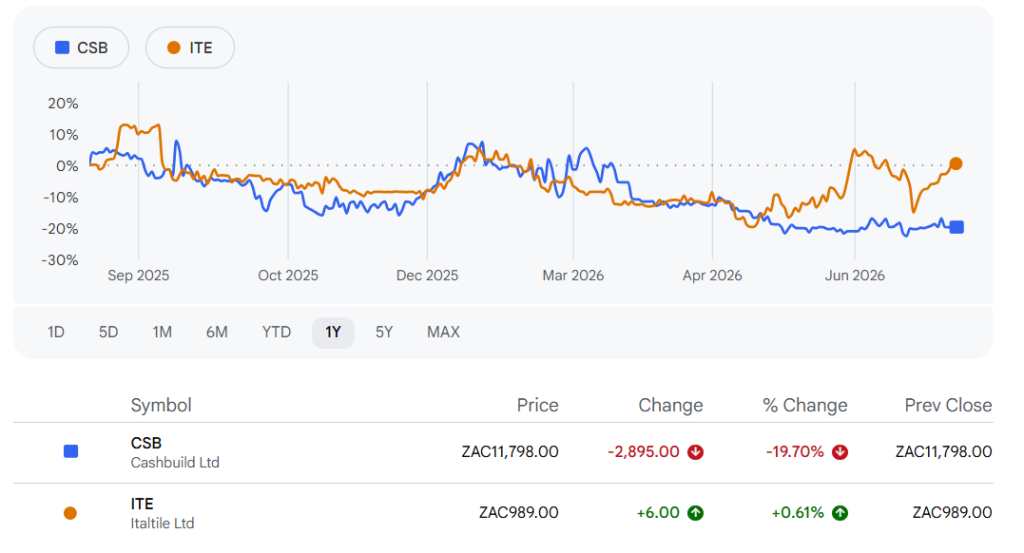
Ghost Bite: For reasons I truly struggle to understand, Italtile’s share price has somehow outperformed sector peer Cashbuild (JSE: CSB) over the past year – despite Cashbuild not having exposure to the manufacturing challenges that Italtile faces!


MTN’s share price takes another knock (JSE: MTN)

Sentiment has soured towards the African telco giant

MTN has already suffered significant selling pressure in the aftermath of the MTN Nigeria numbers that spooked the market. The debate is around how temporary the Q2 slowdown really was in that business.

The group has now added a trading statement for the six months to June into the mix, with a sharp deviation between HEPS and Adjusted HEPS. On the HEPS line, you’ll see an expected move for the period of between -10% and 0%, while adjusted HEPS is expected to increase by between 18% and 23%.

I don’t usually cover EPS because it can be so distorted by impairments and other moves, but it’s worth noting that impairments to operations in Iran (a 49% investment in Irancell) played a substantial role there.

The adjustments to HEPS relate to non-operational items, hyperinflation and a non-recurring deferred tax asset reversal.

The group also notes that total service revenue has grown in line with medium-term guidance, despite a difficult South African prepaid market and the pressures in Nigeria.

Ghost Bite: The market isn’t exactly receptive to the narrative about the broader six months. Instead, investors are focused on the deceleration from Q1 to Q2. This is why the share price has lost 15% of its value in August!


Southern Palladium has been granted a mining right (JSE: SDL)

Now the work really begins at Bengwenyama

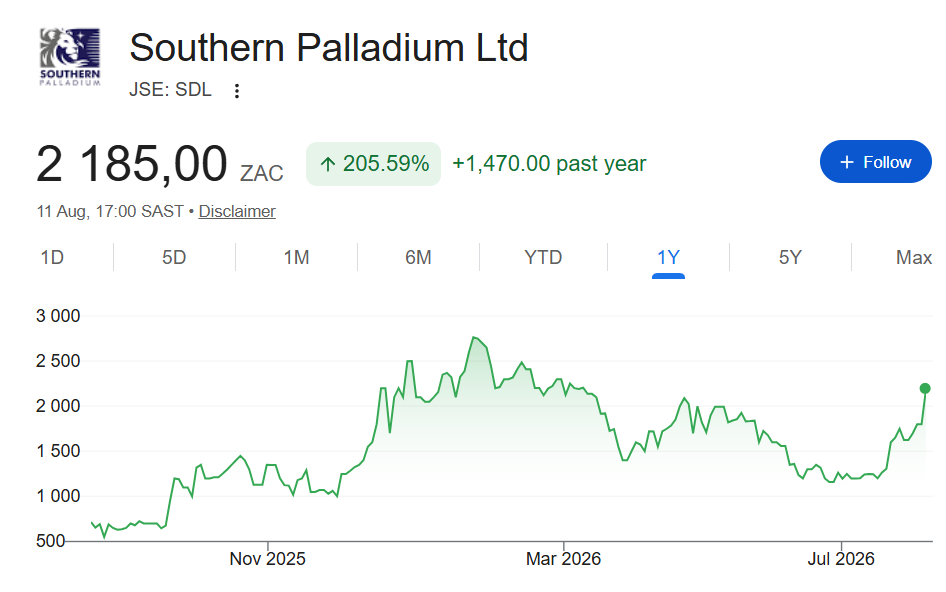
Southern Palladium’s share price jumped 20% after announcing that the mining right has been granted for the Bengwenyama PGM-chrome project. This is the biggest milestone of them all when it comes to junior mining.

Early development work will take place before the end of 2026, while the Definitive Feasibility Study works programme is expected to be delivered in the first quarter of 2027. This delay is being driven by a desire to incorporate the recent metallurgical test results into the plant design and optimisation work.

Ghost Bite: I always chuckle at the fact that that project is owned by a subsidiary called Miracle Upon Miracle Investments. In junior mining, miracles are usually what you need to believe in. Here’s what the share price looks like when miracles happen:


Results of previous poll:


Nibbles:

  • Aveng (JSE: AEG) has released a trading statement ahead of full results scheduled for 24 August. For the year ended June 2026, the headline loss per share improved by between 93.5% and 96.4%. It came in at between 4.2 and 2.3 A$ cents, a minor loss compared to 64.6 A$ cents in the prior period. But it’s still a loss.
  • Brait (JSE: BAT) announced the results of the renounceable rights offer to raise R2.5 billion. Interestingly, Titan and the additional underwriters didn’t need to take up any shares at all. 95.3% of shares were spoken for based on normal rights, with the remaining 4.7% allocated via excess applications. Another useful point is that they received excess applications for 33.1% of the offer, so there was way more demand than supply of the shares!
  • NEPI Rockcastle (JSE: NRP) has signed a €250 million green term loan facility with the European Bank for Reconstruction and Development. The proceeds will be directed to “eligible green projects” that focus on the climate transition objectives. In exchange for being a good corporate citizen, NEPI Rockcastle gets to lock in long-term debt (maturity in 2034) on favourable terms.
  • The Trustco (JSE: TTO) board is clearly rattled by the meeting requisitioned by Riskowitz Value Fund. The purpose of the meeting is to vote on a replacement of the current directors with new directors nominated by Riskowitz. In a clever step to cloud the situation, Trustco approached the Namibian Competition Commission and received an advisory opinion that such a change may contravene the Competition Act unless there is prior notification of such a deal. If you would like to read the opinion, you’ll find it here. So the soap opera continues!

The economy of a mean world

We’ve never had more access to information, and we’ve also never been more anxious. It turns out a frightened population is very good for business.

In the early 1970s, a man named George Gerbner became concerned about what television was doing to people’s perception of the world. So he used his experience as a communications scholar to establish the Cultural Indicators Project, a study aimed at documenting trends in television programming and how these trends changed or affected viewers’ ideas about society.

What he discovered was striking: people who watched large amounts of television were more inclined to believe that the world around them was dangerous, violent or hostile.

Regular TV watchers believed that strangers were threatening, so they didn’t interact with them. They believed that cities were unsafe, so they avoided them. They believed that the future was bleak, which steadily eroded their optimism until many started showing signs of cynicism.

Gerbner named the phenomenon “mean world syndrome”.

By the time he coined the term, Gerbner’s Cultural Indicators Project had catalogued over 3,000 television programmes and 35,000 characters. That was everything that could be found on a handful of channels on 1970s network television. Half a century later in 2026, what we watch and how we watch it would probably blow Gerbner’s mind. We now live in a media environment far more saturated than anything he could have imagined: on-demand streaming services, twenty-four-hour news cycles, ever-present social media. We have access to more entertainment and information than any generation before us.

We’re also more anxious than we’ve ever been. Coincidence?

Seeing is believing

Gerbner’s broader idea was called cultivation theory, and its premise was that media cultivates our worldview as much as it entertains us. Over time, the stories we absorb – whether works of fiction or real news – build a map of what we think reality looks like. Mean world syndrome is what happens when that map turns grim: steeped in violent and frightening stories, we come to believe the world itself must be dangerous. Cultivation theory is the mechanism, and mean world syndrome is one of its symptoms.

Part of why the cultivation theory mechanism works can be explained by the availability heuristic, a mental shortcut first described by psychologists Amos Tversky and Daniel Kahneman in 1973. The availability heuristic means that we judge how common something is by how easily examples of it come to mind. The brain essentially takes a shortcut, and instead of calculating actual odds, it reaches for whatever it can recall most readily and treats that ease of recall as a rough measure of frequency.

It’s an efficient trick most of the time, but there’s a pretty big loophole in it, because how easily something comes to mind has less to do with how often it happens and more with how vivid, recent, or heavily repeated it was.

Say for instance you read a story of a shark attack, which is described in vivid detail. The next time you visit the beach, you may hesitate to get into the water. Even if there has never been a shark attack on that particular stretch of coast, the vividness of the story you read will push the image of a lurking shark to the front of your mind, where it can impact your decision-making.

If you’ve seen ten crime reports this week, break-ins are top of mind and robberies suddenly start to feel commonplace. This is true even if the break-ins were in other countries and your own town is safer than it’s ever been. The footage doesn’t have to be local, or recent, or even representative to shape your sense of the odds. It only has to be memorable.

Then there’s also negativity bias to take into account. Human beings are wired to notice and remember threats more readily than good news. That’s why the story of a neighbour’s kind deed may charm us for a moment, but a report of a violent attack can leave us feeling unsettled for days. This instinct no doubt helped our ancestors to stay alive. But in a saturated media environment, it means the frightening images are the ones that lodge deep and linger longer.

Mad world

Worldwide, an estimated 4.4% of the population lives with an anxiety disorder – around 359 million people as of 2021 (an outdated statistic), which makes it the most common mental disorder on the planet. Women are affected at roughly 1.5 to 2 times the rate of men, and only about 1 in 4 people who need treatment actually receive it. For most of the anxious, in other words, the condition simply goes unaddressed.

South Africa carries a heavier load than the global average. Between 16-20% of people here will experience an anxiety disorder at some point in their lives, and in under-resourced communities the treatment gap yawns wider still. 

Data from the Global Burden of Disease study, which tracks health trends across more than 200 countries, shows the number of people with anxiety disorders climbing steadily since 1990. Then came COVID-19, which sent anxiety and depression rates lurching upward across the world in the early 2020s. 

The steepest increases show up among the young: teenagers and adults under 30 now report anxiety at markedly higher rates than their elders. The median age of onset is just 11 years old.

Gerbner watched a mean world take shape on a handful of channels. The children of the feed grow up with it streaming, unfiltered and unending, from the moment they can focus on a screen.

The business of being afraid

A mean world is more than just a psychological condition. It’s also a market.

Anxiety, it turns out, is enormously good for business, because a frightened person is a motivated buyer. Fear creates a need, and where there’s a need, someone will build a product to meet it (or at least promise to). Entire industries have reorganised themselves around the management of our unease, and since 2020 they have been booming.

Start with the most obvious: the wellness apps. Calm, Headspace and their many imitators have turned meditation – a practice that is, strictly speaking, free – into a subscription economy worth billions. The Calm app alone was downloaded 7.3 million times in 2025. The broader mental-health app market sits north of $9 billion and is forecast to more than quadruple within a decade. The fastest-growing slice of it is “anxiety and depression management”. Therapy platforms like BetterHelp and Talkspace scaled just as fast, meeting a demand for therapy that in-person services could no longer absorb.

The pharmaceutical response followed the same curve. Prescriptions for anti-anxiety and antidepressant medication climbed, and a wave of investment poured into psychedelic therapy like ketamine clinics and companies racing to bring MDMA and psilocybin treatments to market.

But the truly telling growth is at the softer edges, in the vast grey zone of self-soothing where no diagnosis is required and anyone feeling a little frayed is a potential customer. Supplements – whether magnesium, ashwagandha or CBD – became a booming market on the strength of vague promises to take the edge off. So did weighted blankets, aromatherapy diffusers, sleep trackers and mattresses engineered against the insomnia that anxiety breeds.

South Africans know one version of this economy better than most. Private security is one of the country’s great growth industries: some 600,000 registered security officers now outnumber the police by roughly 3 to 1, and the market for smart home security – cameras, sensors, armed-response apps – was worth over $600 million in 2025. It is projected to nearly triple by 2033. 

Some of that spending answers a real and rational danger; after all, South Africa’s crime figures are not a media invention. But some of it answers the feeling of danger, which is a different and more elastic thing – the electric fence raised a little higher, the second camera, the security estate that scans every visitor’s license. Each one is an attempt to buy a peace of mind that never quite arrives, because the mean world always has one more threat to show you.

Even our pets are enlisted: enter the fast-growing market in calming supplements for anxious animals. Herbal and natural formulations now make up around 59% of that market, and roughly a third of pet-supplement buyers have reached for CBD to soothe their dog. We’ve become so fluent in the language of anxiety management that we have begun projecting it onto our animals, treating the family dog for a nervousness that probably says more about the household than the hound.

Flip the switch

No one sat in a boardroom and engineered a nervous planet. But the media environment that cultivates the mean world and the industries that sell relief from it are drinking from the same well. A culture that keeps its people mildly yet chronically afraid has, whether it intends to or not, built an industry that runs on that fear.

The uncomfortable truth is that the mean world is, in a narrow sense, accurate. There really are sharks, break-ins, catastrophes and cruelties, and every one of them really happened. The distortion isn’t in the individual facts but in the proportion – the sheer, relentless volume of frightening signals, delivered without context, absorbed by an ancient brain that treats the vivid as the likely and the memorable as the common. We are not being lied to, exactly. We’re just being shown a true thing so often that it becomes a false picture.

The way out isn’t cynicism, and it certainly isn’t pretending the world is gentle when it isn’t.

It’s perspective, and remembering that the shark story is a story, that the crime report is one event and not a climate, that the feed is a curation and not a census. It’s noticing when a product is selling us calm by first topping up our fear. And it’s occasionally, deliberately, doing the one thing the whole apparatus is built to prevent: looking up from the screen, and checking the map against the territory we can actually see.

About the author: Dominique Olivier

Dominique Olivier uses her love of storytelling and ideation to help brands solve problems.

Her first book, Lessons from Loss, has been published by Penguin Random House.

She is a weekly columnist in Ghost Mail and collaborates with The Finance Ghost on Ghost Mail Weekender, a Sunday publication designed to help you be more interesting.

You can learn more about her work at dominiqueolivier.com and she can be reached on LinkedIn here.

Ghost Bites (MTN Uganda | Schroder European Real Estate | Spur | Thungela)

In this edition of Ghost Bites:

  • MTN Uganda’s results require a careful read
  • Schroder European Real Estate prepares for a “managed wind-down”
  • Spur shareholders must stomach a R129.5 million legal provision
  • Thungela’s earnings and share price chart are world’s apart

MTN Uganda’s results require a careful read (JSE: MTN)

MTN also released an update on the IHS transaction

I’ll get the news re: IHS out of the way first. As you are probably aware, MTN is in the process of acquiring the remaining shares in IHS. With MTN only wanting to buy the African assets (as they want to control more of the value chain), it makes perfect sense that IHS has announced the completion of the sale of its Latam Tower operations in South America. Those assets needed to get out of the way anyway.

Moving on, MTN Uganda has added its name to the recent results released by MTN’s African subsidiaries. To get up the curve on the latest from MTN Nigeria and MTN Ghana, you can refer to this edition of Ghost Bites.

MTN Uganda is generally less volatile than the other subsidiaries. This is because Uganda tends to have a modest inflation rate and a reasonable geopolitical climate. Relative stability is a rare thing in Africa.

Sure enough, for the six months to June 2026, the inflation rate was 3.1% – not much different to the 3.6% in the comparable period.

MTN Uganda grew service revenue by 9.4% over the six months, which is well ahead of inflation. This was driven by 11.2% growth in total subscribers, so their average revenue per subscriber came under pressure in this period. The highlight within service revenue is data revenue, up 15.6% (vs. voice revenue’s gentle uptick of 1.8%).

EBITDA margin is where the struggles begin, as total expenses for the six months increased by 15.1% (with fuel inflation as one of the issues). This is why EBITDA increased by just 4.7%, with EBITDA margin contracting by 250 basis points to 51.2%. To be fair, MTN Uganda’s medium-term EBITDA margin guidance is 51.2%, so they are bang in line with what they’ve told the market they will achieve.

With net finance costs up by 16.6% and depreciation reflecting the underlying increase in assets, you would expect things to be difficult by the time you reach profit after tax. Instead, you’ll find an increase of 37.7%, driven by a 43.1% decrease in the tax charge after a transfer pricing settlement in the prior year.

Profit before tax is thus the cleanest way to consider the numbers, down around 3.5% due to the abovementioned pressures. That’s certainly not a great story, but hopefully the inflationary pressures will abate soon.

Looking at cash flow, total capex was up by a substantial 62.7%. MTN Uganda puts a similar amount into dividends as they do into capex, serving as a good reminder that telco investors are definitely not buying into a capital-light business model.

Ghost Bite: A dependable growth rate in revenue only works well if costs are also dependable. External shocks like fuel inflation are always a risk.


Schroder European Real Estate prepares for a “managed wind-down” (JSE: SCD)

Good riddance to an awful performer

Schroder European Real Estate’s total return over 5 years is -0.13%. Any shareholder who has walked that journey has gone severely backwards vs. inflation. I will remind you that property is an asset class that is supposed to offer really good protection against inflation!

The problem isn’t property as an asset class. The issue is the fund’s strategy, which simply hasn’t worked at all in Europe. I can’t even blame the region, as there are several funds on the JSE that have found success in Europe.

The fund is now preparing for a “managed wind-down” of the company, which is a fancy way of saying that they are throwing in the towel. This means selling the underlying assets and returning capital to shareholders over time. There’s no guarantee of how long this will take, or the prices that will be achieved.

The guidance is for a two-to-three-year process to get rid of the 14 assets strewn across France, Germany and the Netherlands. I somehow doubt that executive compensation will decrease over that period in line with the reduction in assets.

The company also needs to navigate the tax disaster they are dealing with in France.

The immediate next step is for shareholders to vote on the proposed changes to the investment management agreement, as this will give the board the power to move forward with the intended strategy.

Ghost Bite: Absolutely nobody in the local market is going to lose any sleep over Schroder gently disappearing in the coming years. There are so many great property funds on the JSE. This isn’t one of them.


Spur shareholders must stomach a R129.5 million legal provision (JSE: SUR)

Other than this nasty outcome, recent trading looks good

In a matter that dates back to 2019, GPS Food Group sued Spur based on the alleged non-fulfilment of a verbal agreement to acquire, develop and manage a rib processing facility. The parties agreed to refer the matter to arbitration.

GPS put in two claims. Claim A is a damages claim that was estimated at between R119.9 million and R167.0 million. Claim B was an alternative delictual claim of R95.8 million.

The arbitrator issued a part award in August 2025 for Claim A. Alternative Claim B was dismissed.

The arbitrator has now issued the quantum award of damages, with a capital sum of R74.6 million. Together with 10% interest from the date of the original summons and the estimated legal costs, Spur has now raised a provision of R129.5 million. This could be the most expensive order of ribs in history.

The company will lodge an appeal against the award in its entirety, with Senior Counsel having advised Spur that it is likely that the appeal will succeed. Naturally, Senior Counsel will also be billing all the way to the bank, so this legal advice has the same incentive as the turkey voting for Christmas. Spur shareholders will certainly hope that the legal advice is accurate.

In the meantime, the provision is now sitting on the balance sheet. It’s also directly hit earnings, which is why Spur’s HEPS for the year ended June 2026 is expected to drop by between 34% and 43%.

Underneath all this noise, there’s actually a solid result from the group’s operations. They’ve released an adjusted HEPS number that excludes the claim provision. On this basis, adjusted HEPS would be up by between 5% and 13%, coming in at between 356.87 cents and 384.06 cents.

The midpoint of 370.47 cents is the number that the market will use to value the shares, less an allowance for the legal claim. With a market cap of nearly R3.8 billion, the claim is irritating, but not an existential crisis.

Based on Friday’s closing share price of R41, Spur is trading on a P/E of roughly 11x.

Ghost Bite: The stock barely reacted to the news of the claim. Either shareholders were expecting it, or people had already left their desks for the long weekend. We will find out on Tuesday which one it is.


Thungela’s earnings and share price chart are world’s apart (JSE: TGA)

Many mining companies have been a net beneficiary of the conflict in Iran

When global supply chains clog up, commodity prices tend to increase rapidly. It’s the classic supply and demand balance – or in this case, imbalance. And if fuel prices move sharply higher as well, then the price of commodities can do some particularly crazy things.

If you look at a year-to-date chart of coal futures and various benchmark prices, you’ll see that there was a considerable spike in March. For example, Richards Bay Coal futures are up 23.4% year-to-date. Newcastle Coal Index futures are up by roughly 20% this year as well. These are the two benchmark prices that matter for Thungela, as the company has coal operations in both South Africa and Australia.

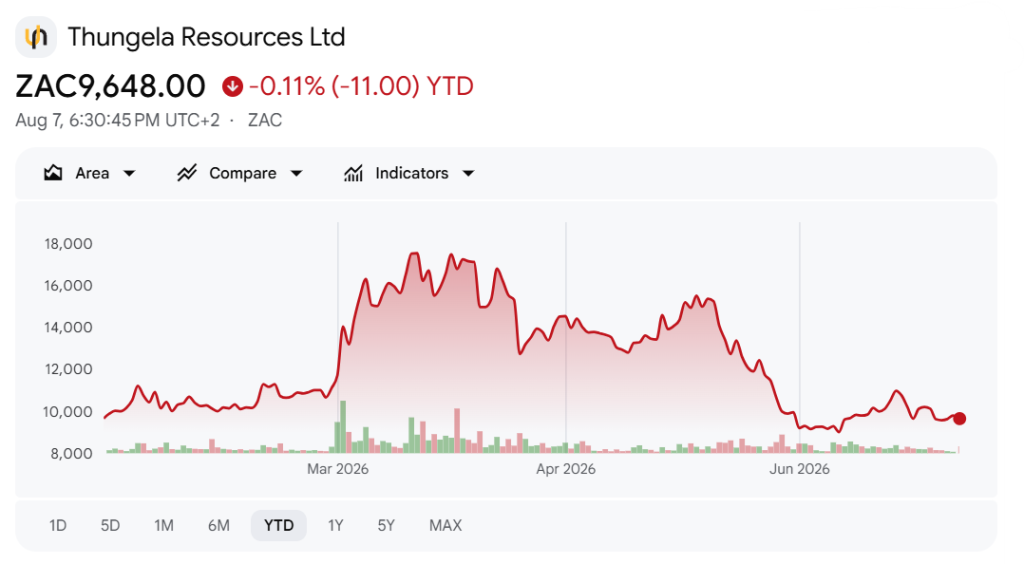
With such favourable moves in the underlying commodity price, you would expect to see plenty of fireworks in the share price. As is so often the case with mining stocks though, the chart is a cruel tale of what might have been:

The chart is even more depressing in the context of the latest trading statement. For the six months ended June 2026, Thungela expects HEPS to be between R4.60 and R4.95 – an increase of between 140% and 158%!

Even on a 12-month basis, the total return for shareholders has been 7%. Yes, that’s the return including dividends. This feels like nothing at all compared to the underlying jump in earnings.

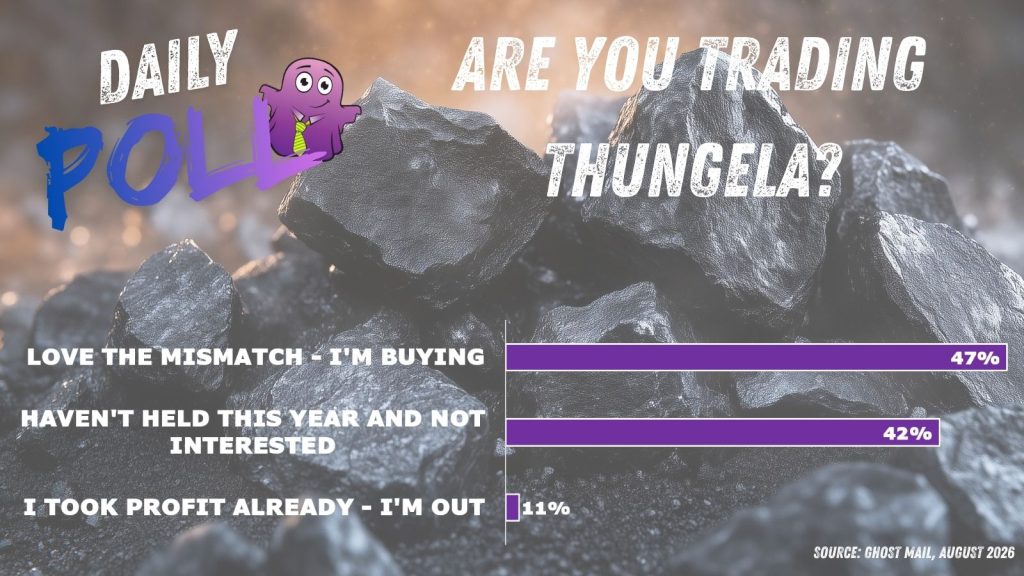
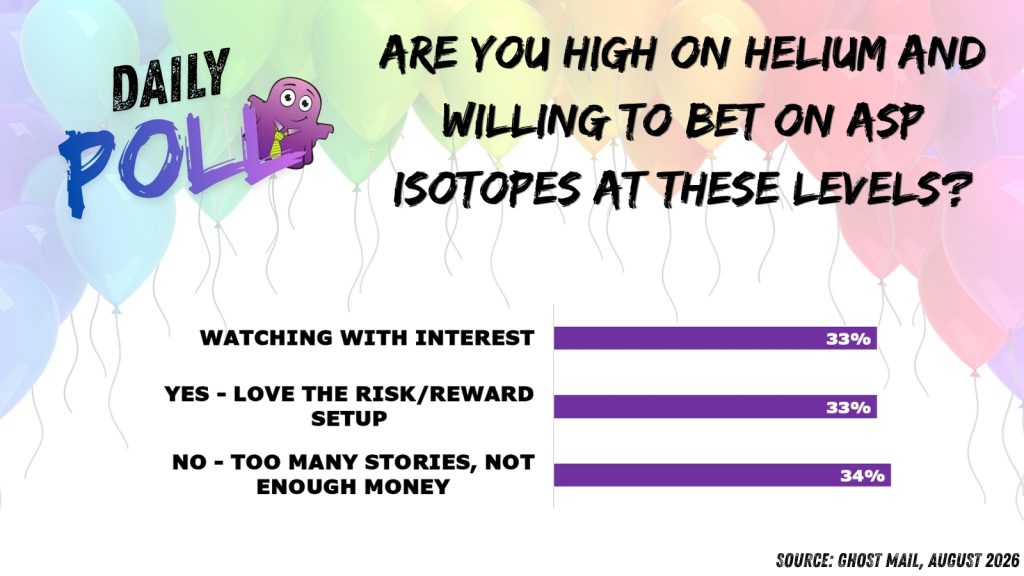
Ghost Bite: The disconnect between mining share prices and the underlying earnings can be very difficult to navigate. Coal prices are still much higher than they were at the start of the year, yet Thungela’s share price has given up all its year-to-date gains. Let me know in the poll what your plan is here!


Results of previous poll:


Nibbles:

  • Director dealings:
    • The CEO of Shuka Minerals (JSE: SKA), Richard Lloyd, has bought around R430k worth of shares in the company. This increases his stake to 2.05%.
  • Accelerate Property Fund (JSE: APF) is in the naughty corner at the JSE. The REIT earned itself a public censure and a R500k fine (suspended for three years) based on the decision to appoint Flanagan & Gerard as managers of Fourways Mall. This should’ve only been done with shareholder approval. As you might have guessed, such approval was never obtained. To this day, Flanagan & Gerard are still in place on a month-to-month basis, a situation that the JSE has now instructed Accelerate to rectify with a shareholder vote. Based on how much better things are at Fourways Mall these days, the censure is cheap at the price. Accelerate better get on the right side of the JSE very quickly though, as this is never a good look.
  • After the latest round of on-market purchases, Novus (JSE: NVS) now has a direct stake of 51.91% in Mustek (JSE: MST). Together with concert parties, the stake is up to 72.20%.
  • Eastern Platinum (JSE: EPS) has announced that Chairman Changyu Liu will become the interim CEO in the wake of Wanjin Yang’s sudden departure. I must point out that the company also replaced its CFO just a couple of months ago. I don’t know what is going on in that boardroom, but the market doesn’t enjoy stuff like this.

Ghost Bites (Copper 360 | Pick n Pay | Quilter | Sappi)

In this edition of Ghost Bites:

  • Copper 360 pulls a rabbit out of the hat with Neal Froneman
  • Pick n Pay’s grocery business is showing some positive signs
  • Quilter’s distribution model shines through once again
  • Sappi’s outlook for the fourth quarter gives speculators something to latch onto

Copper 360 pulls a rabbit out of the hat (JSE: CPR)

As announcements of new Chairmans go, this is a big one

Copper 360 has been a less-than-joyous story for investors. In fact, it’s been catastrophic. The share price has shed nearly 90% of its value over three years.

But out of nowhere, like Gandalf arriving at Helm’s Deep at first light on the fifth day, a saviour has emerged. Rupert Smith has retired as Chairman, making space for none other than Neal Froneman (of Sibanye-Stillwater fame) to be appointed as an independent non-executive director and Chairman of the board.

Ghost Bite: Within an hour of this announcement, the share price had shot up 18%. I’m not surprised at all.


Pick n Pay’s grocery business is showing some positive signs (JSE: PIK)

Comparing the like-for-like growth to Boxer is interesting

Pick n Pay has added its name to the list of recent retail updates on the JSE. We know that the apparel retailers have been struggling with weak sales this winter. But how did Pick n Pay do?

This retailer is still deep in turnaround mode, so they are closing or converting underperforming company-owned supermarkets. This means that total group turnover was flat for the 20 weeks to 19 July 2026. Pick n Pay’s like-for-like sales growth was 2.6% overall.

If we focus on the South African business, we find 1.9% like-for-like growth in South Africa vs. a 0.4% decline in total turnover. The impact of store closures is more than offsetting the like-for-like growth. Internal selling price inflation was 1.3%, lower than the 1.9% in FY26. CPI Food inflation was 2.5%, so Pick n Pay is having to implement below-inflation increases to compete.

The odd situation around company-owned vs. franchise stores continues, with company-owned supermarkets growing like-for-like sales by 3.3% (and volumes up by 2.0%). The franchise stores could only manage like-for-like growth of 1.3%. I still scratch my head about how a store with a salaried manager can be outperforming a franchisee who has invested a fortune in their store, but there we have it. This has been going on for a couple of years now.

The online business grew by a solid 37.5%, so Pick n Pay isn’t being completely left for dead by Shoprite (JSE: SHP) and their Sixty60 offering, or Woolworths (JSE: WHL) with Dash.

On the clothing side, clothing sales in standalone stores decreased by 1.3% on a like-for-like basis. That’s a poor performance for a value-focused clothing retailer, even in the context of recent struggles for SA consumers. At least it’s better than the terrible -5.6% they reported in the second half of FY26. Total clothing sales increased by 3.3%, so they are opening more clothing stores while they close underperforming grocery stores.

The company is still busy with the s189 process to try and rectify the labour costs in its stores. As you can imagine, the trade unions are all over this thing. It’s sad that years of poor decision making at head office will lead to job losses in the stores, but that’s unfortunately how these things go. It’s why executives get paid a lot of money, as they have a responsibility that filters all the way down.

To end on a positive note, keep in mind that Pick n Pay still has a controlling stake of 53.1% in Boxer (JSE: BOX). As we know from Boxer’s recent update, that excellent retailer grew sales by 2.2% on a like-for-like basis in the latest period. It’s interesting to note that this was only 30 basis points ahead of Pick n Pay South Africa!

But if you strip out the relative inflation in both businesses, the gap is larger, as Boxer had to navigate deflation of -1.9% vs. Pick n Pay’s 1.3%. Importantly, both still achieved positive volumes.

Ghost Bite: Other than the concerning performance in Pick n Pay Clothing, this looks like one of the better recent updates from the embattled retailer.


Quilter’s distribution model shines through once again (JSE: QLT)

Strong distribution is the real moat in wealth and asset management

Quilter, the UK-based asset and wealth manager with a strong distribution model, has reported results for the six months to June 2026.

By going out and hunting for assets, rather than hoping that airport ads will do the trick, Quilter tends to achieve solid inflows. This period was even better, with record core net flows of £6.0 billion (up 32%). Importantly, this represents 9% of their opening assets under management and administration (AUMA).

Together with positive market movements, AUMA ended the period 11% higher than at the end of December 2025. Remember, this is growth for only six months!

Revenue was up 12%, with management fees on assets driving their growth. Cost growth was 13% though, so this was a period of heightened investment in the platform. Adjusted pre-tax profit grew by 12%.

HEPS is far less exciting than adjusted earnings, dipping from 3.4 pence to 3.3 pence per share. The group would instead like you to consider adjusted diluted earnings per share, with an increase of 13%.

The answer, as usual, is probably somewhere in the model. Cash remains king in this world, with the interim dividend up by 5%.

The company is executing significant share buybacks. It looks like they bought back roughly £60 million in shares in this period based on the timing of the tranches. This is part of a broader £100 million programme to be completed by the end of the year.

For context, interim adjusted profit before tax was £112 million. There’s a lot of cash flowing back to shareholders at the moment.

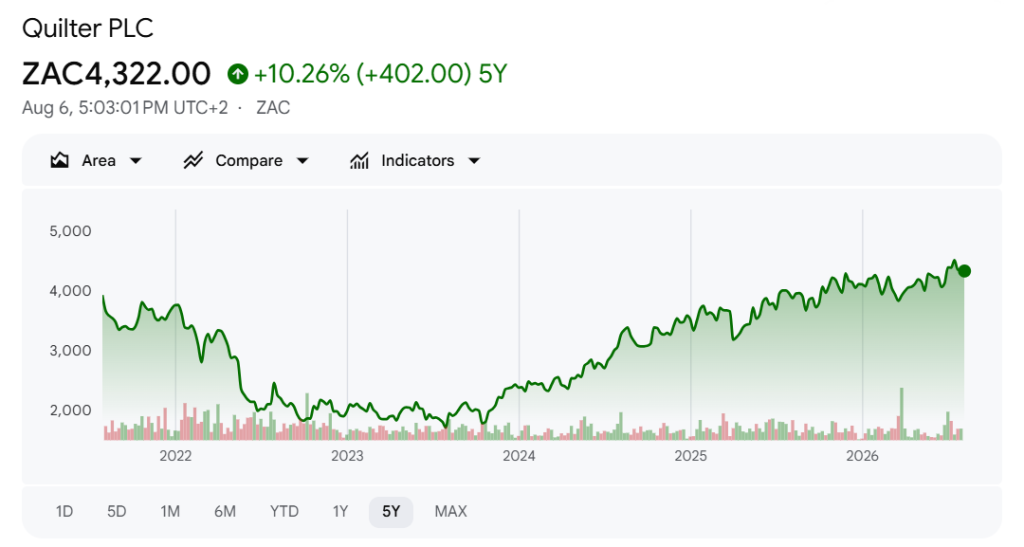
Ghost Bite: In my opinion, asset and wealth management firms should be judged primarily on inflows. On that metric, Quilter tends to be a strong performer. They have various distribution channels that performed really well in this period. That’s why the share price looks like this:


Sappi’s outlook for the fourth quarter gives speculators something to latch onto (JSE: SAP)

But I’m still avoiding this one

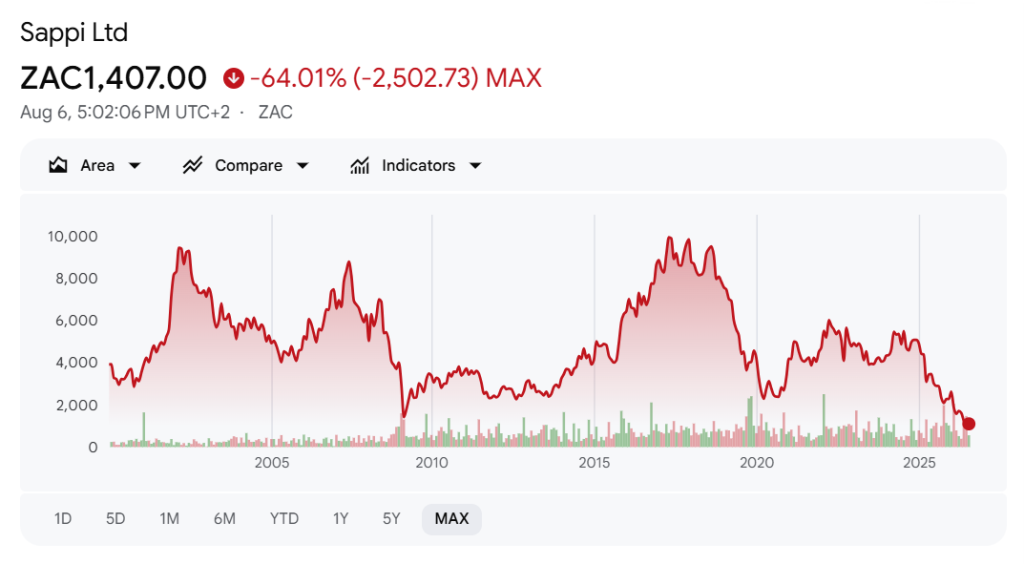
Sappi’s share price closed 12.6% higher after the release of results for the third quarter of 2026. Before I go any further, let me zoom out to give you full context:

As you can see, the latest move doesn’t even register on a long-term chart. If you ever wondered what a cyclical share price chart looks like, you now have your answer.

It’s not like the numbers were anything to feel good about when viewed in isolation. Revenue was up by just 1%. Adjusted EBITDA fell by a nasty 34%. The headline loss per share worsened from 5 US cents to 27 US cents. On top of all this, net debt was up 3%.

If you can believe it, this is “in line with the improved guidance” given to shareholders. Talk about low expectations!

Escalating fuel costs just added fuel to the fire, with Sappi already dealing with multiple challenges in its business. Selling prices are under pressure across most of Sappi’s product categories. An increasingly digital world is a hostile place for paper and pulp.

The “highlight” was packaging and speciality papers, where volumes were up 14%. But those inverted commas are critical, as profitability actually declined in this sector on a year-on-year basis, not least of all due to a scheduled maintenance shut.

To their credit, profitability in the graphic paper segment was only marginally lower than the prior year. There’s been a lot of focus by management on right-sizing and restructuring this part of the business. Sales volumes fell 6% though, so they appear to be fighting a losing battle.

So, why did the share price go up?

The answer lies right at the bottom of the announcement, with Sappi estimating that adjusted EBITDA for the fourth quarter will be “materially above that of the third quarter”. Given that adjusted EBITDA was just $53 million for Q3 and that Sappi reported a net loss of $181 million, adjusted EBITDA will need to be 4x higher just to get them into the green.

Ghost Bite: Every now and then, I’m tempted to take a speculative position based on the long-term chart. But each time, I stop myself based on the demand trends for Sappi’s products. I fear that this cyclical business has slipped into structural decline.


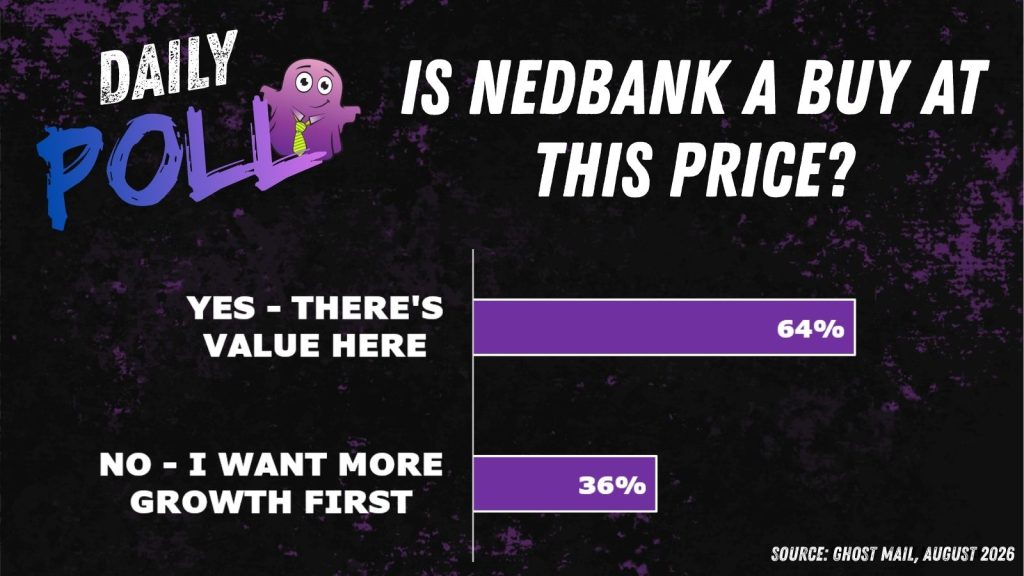
Results of Nedbank poll:


Nibbles:

  • Director dealings:
    • An executive member of the board of Richemont (JSE: CFR) sold shares worth nearly R35 million. That’s a nice payday for somebody! As the company is Swiss, we have no idea which director actually sold the shares, so it really is “somebody” in this case.
    • The CEO of Sirius Real Estate (JSE: SRE) sold shares worth around R11.2 million. That’s a significant trade, although his remaining stake in the company is worth more than R280 million.
    • The CEO of Salungano (JSE: SLG) bought shares worth over R3.3 million.
  • ASP Isotopes (JSE: ISO) has announced a take-or-pay deal at Renergen. And no, it’s not for helium! This is a liquefied natural gas (LNG) transaction with a domestic food processor. This five-year take-or-pay contract does what it says on the tin, with Renergen now sitting with secured contracts that underpin 75% of the LNG volumes in Phase 1. Of course, the market is waiting nervously for helium production to start, with big promises being made about this happening in the coming months.
  • Montauk Renewables (JSE: MKR) published results for the six months to June 2026. This stock is well off the beaten track on the JSE, so I’m just giving them a mention down here. Although revenue was up by 14.5% and EBITDA jumped by 85.4%, this was still only good enough for the company to creep into the green at headline earnings level. They moved from a headline loss of $4 million in the comparable period to headline earnings of $1.1 million in this quarter. That’s just $0.01 per share in HEPS vs. a net asset value per share of $1.85. Not exactly a money spinner, is it? The share price has shed a whopping 83% over 3 years!
  • As regular readers know, Brait (JSE: BAT) is busy with a value unlock strategy that has included asking shareholders for more money. Odd, I know. Part of the plan is to make changes to the capital structure, with the relevant transaction steps requiring holders of exchangeable bonds to vote in favour of the transaction. The good news is that bondholders are playing ball, with the terms and conditions successfully amended. Shareholders are watching with scepticism though, evidenced by the resolution at the AGM that deals with the board’s authority to issue ordinary shares. 49.5% of votes at the meeting were cast against this resolution!
  • Southern Palladium (JSE: SDL) requested a trading halt on its ASX listing. We’ve finally seen some sense prevail here, as the JSE has also halted trade in the shares. Usually, the halt is only on the ASX and not on the JSE! Under ASX rules, a halt is needed pending the release of an important announcement. We will now wait and see what it is.
  • Sable Exploration and Mining (JSE: SXM) has successfully convinced the JSE that the transaction with Daemaneng Minerals re: the management of the Lapon beneficiation plant is in the ordinary course of business. It’s simply the appointment of a contractor. It’s therefore not going to be considered a Category 1 transaction. Sable has avoided an onerous outcome here.

Who’s doing what this week in the South African M&A space?

0

Datatec subsidiary Logicalis USA has acquired Loial, a New Mexico-based technology solutions provider for an undisclosed sum. The acquisition was effective on 31 July 2026.

Stor-Age has announced the acquisition of a portfolio of 10 self-storage properties from Xtraspace Properties for R387 million. The proposed transaction is expected to be earnings accretive on a per-share basis. The company simultaneously concluded a management agreement to manage a further six Xtraspace self-storage properties.

At an extraordinary general meeting this week IHS shareholders approved MTN’s US$2,2 billion acquisition of the remaining 75.3% stake in IHS. The deal was announced in February 2026. This fulfils one of the conditions precedent to the transaction.

The Legends Agency, headquartered in Cape Town, has secured £1 million in investment from Effer Ventures, an operationally focused growth investor, backing UK-based services businesses with a particular focus on staffing and recruitment. The Legends Agency, which was founded in 2020, is an independent offshoring and Employer of Record provider specialising in South African talent. The funding will support the company’s next phase of expansion.

SA-H2, a blended finance private equity fund managed by Climate Fund Managers, has reached its first close at R3 billion. The fund invests in large-scale energy transition projects across the green hydrogen value chain, including green hydrogen production, downstream derivatives such as green ammonia and green methanol and the decarbonisation of hard-to-abate industries. Commitments were secured from fund anchors Invest International and the European Commission via its Global Gateway strategy as well as from the Industrial Development Corporation of South Africa (IDC), the Public Investment Corporation (PIC) and Sanlam Life.

Pan-African fintech company Moment has closed a US$22 million Series A round led by AlphaCode Venture Partners with continued investment from MultiChoice, General Catalyst and fresh investment from Canal+. Moment was established in 2022 as a joint venture between MultiChoice and Rapyd, a digital payment processing and fintech services company. The funding will be used for expansion across the continent, to deepen its network and enhance its platform.

Kleoss Capital has made an investment into IMT – Integrated Mining Technologies alongside IMT management, the Gert Roselt Family Trust, AWCA Investment Holdings and Ditiro Capital.

Epiroc, a Swedish manufacturer of mining and infrastructure equipment, is to acquire Eventspec, a South African mining aftermarket solutions provider. Eventspec manufactures parts for drill rigs, mine trucks and loaders and provides related rebuilds, repairs and services. Financial details were undisclosed.

Weekly corporate finance activity by SA exchange-listed companies

0

Africa Bitcoin has conditionally raised £250,000 (R5,54 million) by way of a placing of 1,086,957 shares at a price of 23 pence (R5.10) per share. Following the company’s successful application to list on the Access segment of the Aquis Growth Market, trading of its ordinary shares is expected to commence on 17 August 2026.

Novus has acquired an additional 60,487 Mustek shares at an average R15.00 per share on the open market (outside of the Mandatory Offer) for R907,305. The company now holds 29,16 million Mustek shares constituting 50.68% of the issued shares in Mustek. Together with concert parties this shareholding increases to c.70.97%.

Glencore announced in its interim results that the company intends to apply for a secondary listing (via CDIs) on the ASX, targeting admission in October 2026.

Shareholders have approved the name change of Capitec Bank Holdings to Capitec Limited. The company will trade under the new name from commencement of trade on 26 August 2026.

Old Mutual’s secondary listing migration from the Zimbabwe Stock Exchange to the Victoria Falls Stock Exchange has been approved. The company’s shares will commence trade on the VFEX from 12 August 2026.

In July 2025 African Dawn Capital was suspended for failing to publish its audited annual financial statements within the prescribed period for the year ended 28 February 2025. The company intends to publish these and interim financial results for the six months ended 31 August 2025 by 31 August 2026. The company will then apply to the JSE for the lifting of the suspension.

The JSE has advised shareholders of Sebata that the company has failed to submit its annual report within the four months period as stipulated by the Listing Requirements. Should the company fail to submit its annual report before 31 August 2026, its listing may be suspended.

Areit Prop remains suspended on the JSE for failing to publish its annual financial statements for the financial years ended 31 December 2023, 2024 and 2025. The company has informed shareholders in its quarterly update that while making progress on bringing its reporting up to date the Board will also be considering the company’s potential delisting – a decision it will only take once the financial reporting has been bought up to date.

Aimia repurchased and cancelled a total of 174,750 shares during July 2026, representing 0.2% of the company’s issued share capital. The shares were repurchased at a weighted average price of C$2.67 for a total consideration of C$467,258. In June, the company announced the renewal of its repurchase programme of up to 5,012,419 shares. The programme will run through to June 2027.

During the period 2 June to 4 August 2026, Kal Group repurchased 2,290,091 shares for an aggregate R111,86 million. The shares will be delisted. The company may repurchase a further 12,57 million (16.92%) of the shares in issue in terms of the authority granted.

On 5 August 2026, Glencore announced a top-up shareholder return of $15 billion to be effected by way of a c.$1 billion special cash distribution of $0.085 per share, and a new $500 million buyback programme intended to run through to February 2027. The special distribution will be paid in September 2026.

To reduce the share capital of the company and return capital to shareholders, Quilter commenced, in March 2026, a £100 million share buyback programme. The maximum aggregate purchase price payable by the company under Tranche 2 is up to C.£30 million. During the period 27 to 31 July 2026, Quilter repurchased 75,000 shares on the LSE with an aggregate value of £146,644 and 15,000 shares on the JSE with an aggregate value of R652,252.

In June, Greencoat Renewables announced its intention to commence a second tranche of the repurchase programme which will return a further €25 million of capital to shareholders. The second tranche repurchase will be complete by end-December 2026. This week 1,070,832 shares were repurchased for an aggregate €844,257.

Bytes Technology announced in May 2026 its intention to implement a new share repurchase programme to purchase the company’s shares for an aggregate value of up to £25,0 million. This week the company repurchased 420,000 shares at an average price per share of £4.05 for an aggregate £1,71 million.

British American Tobacco has again extended its share buyback to end on 12 October 2026. All shares repurchased will be cancelled. Over the period 27 to 31 July 2026, the company repurchased a further 641,197 shares at an average price of £46.13 per share for an aggregate £29,56 million.

Ninety One plc announced an increase in the repurchase programme from £30 million to £55 million to be completed in July 2026. The shares, to be purchased on the open market, will be cancelled to reduce the Company’s ordinary share capital. Over the period 27 to 31 July 2026, the company repurchased a further 732,624 ordinary shares at an average price 213 pence for an aggregate £1,56 million.

Anheuser-Busch InBev’s US$6 billion share buy-back programme continues. The shares acquired will be kept as treasury shares to fulfil future share delivery commitments under the group’s stock ownership plans. During the period 27 to 31 July 2026, the group repurchased 318,118 shares for €22,91 million.

During the period 27 to 31 July 2026, Prosus repurchased a further 1,837,240 Prosus shares for an aggregate €71,67 million and Naspers, a further 595,079 Naspers shares for a total consideration of R501,41 million.

One company issued a profit warning this week: Accelerate Property Fund.

One company renewed its cautionary notice: Sebata.

Who’s doing what in the African M&A and debt financing space?

0

HSBC Holdings has agreed to sell the retail banking business of its indirect subsidiary, HSBC Bank Egypt, to Emirates NBD Egypt, which is a direct subsidiary of Emirates NBD Bank PJSC. The agreement covers HSBC Egypt’s entire retail banking business, including retail loans, deposits, customer accounts and the employees supporting the business. Financial terms were not disclosed.

Moove, the Nigerian-born, global mobility fintech, has raised US$250 million (at a $2,1 billion valuation) in a Series C funding round led by Mubadala Investment Company and co-led by Woven Capital, Toyota’s Growth Fund, and Ion Pacific. Other investors included BlueCrest Capital Management, Sona Asset Management, The Raptor Group, BlackRock, MUFG, Franklin Templeton, Uber, Left Lane, Silverbacks Holdings, Square Associates, The Latest Ventures, Endeavor Catalyst, and the Ontario Power Generation Pension Plan.

Stablecoin, a payments infrastructure for emerging markets, enabling international payments, treasury management, and access to hard currency liquidity, has secured US$40 million from SC Ventures by Standard Chartered, Sony Innovation Fund, Polychain Capital, Blockchain Capital and additional strategic investors.

Beltone Venture Capital announced the successful partial exit from Egyptian proptech BirdNest, delivering a 3.5x return on invested capital and an 80% internal rate of return (IRR) over a two-year holding period. The partial exit was executed across Beltone Venture Capital’s direct stake and its indirect stake through the joint fund with UAE-based Citadel International Holdings, while Beltone Venture Capital continues to retain a strategic stake in BirdNest, reinforcing its confidence in the company’s long-term growth potential.

AVA Capital, the integrated financial services group was admitted to the Nigerian Exchange by way of listing by introduction on 31 July 2026.

African Export-Import Bank (Afreximbank) has concluded financing facilities totalling US$190 million for CBZ Bank Limited of Zimbabwe. The first facility is a $150 million revolving trade finance facility for CBZ Bank Limited; the second facility is a $20 million dual-tranche SME finance facility and finally, the two institutions also signed an agreement for a $20 million dual-tranche on-lending facility to CBZ Bank Limited.

Ghost Bites (ASP Isotopes | Glencore | Sasol | Sabvest | Super Group)

In this edition of Ghost Bites:

  • ASP Isotopes is “at an inflection point” in its business
  • Glencore made a killing in the six months to June
  • Sasol’s second half saw earnings triple sequentially
  • Sabvest keeps on delivering
  • Super Group lives up to its name

ASP Isotopes is “at an inflection point” in its business (JSE: ISO)

All eyes are on helium

ASP Isotopes has been working the storytelling angle of its business with great enthusiasm. They held an investor event focused on the helium assets that they acquired in Renergen. They’ve also released a shareholder letter, as well as a presentation delivered at a conference.

As a general comment, I feel that the company releases too many SENS announcements of a non-financial nature. I get the need to keep investors interested while the company works towards properly monetising its technology, but eventually investors just switch off until there’s cash flow to talk about.

In the latest letter, the CEO notes that three of the business units “appear at an inflection point and are expected to make substantial contributions to achieving profitability in the near term.” Exciting, but still a leap of faith that South African investors aren’t famous for being willing to take!

To give you an idea of the rapid growth forecast, the PET Labs business is expected to make revenue of $14 million in FY26 (vs. $6 million in FY25). The long-term target is $50 – $100 million in EBITDA by 2031. Yes, that’s just five years away.

The group-level 2031 EBITDA target is between $330 million and $700 million. Forecasting risk? Very, very high. Potential upside? Also very high!

Over at Renergen, helium production is expected to begin before the end of September 2026. This will be a huge moment for the company and for South Africa. We can only hope that this happens, particularly as ASP goes into great detail on why helium shortages are becoming a global crisis and how Renergen’s production can help close that gap.

The Silicon-28 and Ytterbium-176 enrichment facilities are expected to ship initial product during the second half of 2026. This comes after many delays that the company has blamed on OEM equipment suppliers rather than the underlying technology developed by the company. This is genuinely cutting-edge science. If they had Iron Man hiding in a cupboard at that facility, it wouldn’t surprise anyone.

To try and achieve some earnings visibility, the company is negotiating various take-or-pay supply agreements with potential large global customers. When the word “potential” goes away, the share price trajectory will start turning.

The broader strategy to unlock value is to separately list the underlying subsidiaries that have different (but complementary) technologies. ASP will own majority stakes in these underlying subsidiaries. I must say, that sounds a lot like a scenario where a massive conglomerate discount will be applied to the holding company, but only time will tell.

In line with this strategy, they are currently working on a planned reverse merger between Renergen and Noble Africa, with ASP set to hold 89% of the combined company. They are also dressing up Quantum Leap Energy for a separate listing. As a new name in this story, ASP has set up Alpa Theranostics as a biotechnology company that will move into human clinical trials in the next 12 months.

I’ll end off on something I love: the PET Labs business provides treatments to children under the age of 18 free of charge. It’s hard not to applaud an initiative like this for childhood cancer and other horrors.

Ghost Bite: If the helium promises are kept, that really will be an inflection point for Renergen.


Glencore made a killing in the six months to June (JSE: GLN)

The company knows how to pounce on a disrupted energy market

Glencore has signed off on an extremely lucrative period. In a supply-constrained environment for global commodities thanks to the Iran conflict, the company was able to position its businesses in a way that worked out beautifully.

How beautifully, you ask? Well, with revenue up by 49%, you need to brace yourself for some impressive swings further down the income statement.

Group adjusted EBITDA increased by 86% to $10.1 billion. Within that number, the biggest excitement was the Marketing business, where adjusted EBIT jumped by 142%. This is where Glencore made the most of the supply chain disruptions and associated energy trading opportunities.

Just like the other major names in mining, Glencore is investing heavily in copper. This is part of why net capex on property, plant and equipment increased from $3.2 billion to $4.0 billion.

Cash profits were more than high enough to cover the uptick in capex. In fact, group net debt declined by $1 billion during the period. The net debt to adjusted EBITDA ratio sits at a comfortable 0.56x, down from 0.83x.

With the level of debt in the business in line with the self-inflicted cap of $10 billion, Glencore has enough confidence to pay a top-up special cash distribution of around $1 billion. They’ve also announced a new $500 million share buyback.

Looking ahead, Glencore expects continued strong cash generation in the second half of the year. Although it’s nearly impossible to estimate with any accuracy, they’ve guided 2026 adjusted EBITDA of $19.7 billion (up 46% vs. the prior year’s $13.5 billion).

The company plans to take this story to Australia, with a secondary listing on the ASX targeted for October 2026. There’s a vast pool of capital in that market that loves mining stocks.

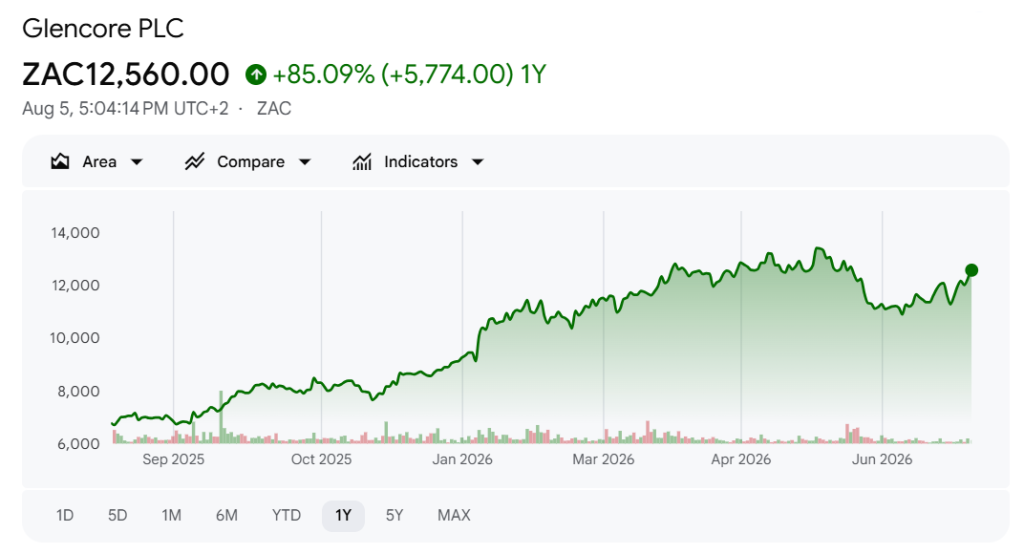
Ghost Bite: The share price is up 85% over 12 months. You may be tempted to think that most of that happened after the Iran conflict, but that’s actually not the case:


Sasol’s second half saw earnings triple sequentially (JSE: SOL)

They would’ve been a lot better if not for rand appreciation

Most of us want to see a strong rand, as it (usually) keeps fuel prices at bay and helps us afford those imported goodies that we all like. But exporters absolutely don’t want to see a strong rand. With much of South Africa’s industrial base focusing on export sales due to weak domestic demand, the change in trajectory of the USD/ZAR exchange rate has been a challenge.

Sasol is one such company, with the double-whammy impact of offshore earnings that need to be translated back to rand.

In a trading statement covering the year ended June 2026, Sasol confirmed that HEPS should increase by between 2% and 14% vs. the prior year. This isn’t nearly as exciting as the 12% to 20% increase in adjusted EBITDA, so there are clearly a number of important movements happening between EBITDA and HEPS.

Before we get to that, we can deal with the positive drivers of performance. As indicated in Sasol’s recent performance metrics release, the company enjoyed a 4% increase in sales volumes thanks to improved production. A 7% increase in the USD crude oil price also helped, as did a more than 100% increase in refining margins.

The 7% appreciation of the rand against the US dollar blunted these gains, as did substantial losses on monetary assets and liabilities. I’ll wait for the full numbers, but I suspect that’s why EBITDA looks so much better than HEPS, as those losses would be happening below the EBITDA line.

Impairments don’t affect HEPS, but they are worth digging into. Impairments were R16.8 billion in this period – lower than R20.7 billion in the prior year, but still an immense number. This includes costs capitalised to the Secunda liquid fuels refinery (still fully impaired), as well as impairments to the assets of the polyethylene business and the production sharing agreement in Mozambique.

Sasol has also warned shareholders that free cash flow won’t look as good as earnings. This is due to elevated levels of working capital, driven by the Middle East conflict (among other issues).

But here’s the point that you really need to keep in mind: HEPS was down 34% year-on-year at the halfway mark of the year. They generated R9.27 in the first six months of FY26. In the second half, they achieved between R26.73 and R30.73.

This means that HEPS tripled sequentially. That’s why the share price is up 73% year-to-date as a proxy for the oil price, even if you can’t see the growth coming through in full-year earnings.

Ghost Bite: The first half of the year is a cautionary tale for the Sasol bulls. The share price was down 1% on the day of this trading statement, so the market is clearly worried about the oil price running out of puff.


Sabvest keeps on delivering (JSE: SBP)

The market has reduced the discount per share to just 17%

As investment holding companies go, Sabvest has one of the best reputations on the JSE (if not the best reputation). They have an interesting, diversified portfolio of assets that you can’t get your hands on anywhere else. Most importantly, they have a great track record of value creation.

The team has done it again, with net asset value (NAV) for the six months to June 2026 expected to increase by between 18% and 24% over the past 12 months. Most of that move happened in the first six months though, as the NAV per share is only up by between 1.7% and 6.9% since December 2025.

The current share price is R139, which is a discount of only 17% to the mid-point of the guided NAV per share. When detailed results are released in mid-to-late August, investors will be able to decide if that’s reasonable or not.

Ghost Bite: Sabvest’s total return over the past year is nearly 50%. The market has reduced the discount to NAV to a level that you’ll rarely see in an investment holding company.


Super Group lives up to its name (JSE: SPG)

The trading statement for the year ended June 2026 looks great

Whenever I see a trading statement covering a 12-month period, I always look for the interim earnings to give more context. At Super Group, they grew HEPS from continuing operations by 28% in the six months to December 2025, so the first half of the year got them off to a fantastic start.

The second half was even better, as the year ended June 2026 is expected to reflect HEPS growth of between 33.6% and 40.9%. This is from continuing operations, an important lens to apply due to the disposal of SG Fleet.

They describe the period as being characterised by most of the businesses performing strongly and gaining market share. There are a number of difficult macroeconomic issues at play, but you would never guess it by looking at these numbers!

Ghost Bite: Results are due for release on 8 September. With the share price closing 5% higher on the day, the market is looking forward to them.


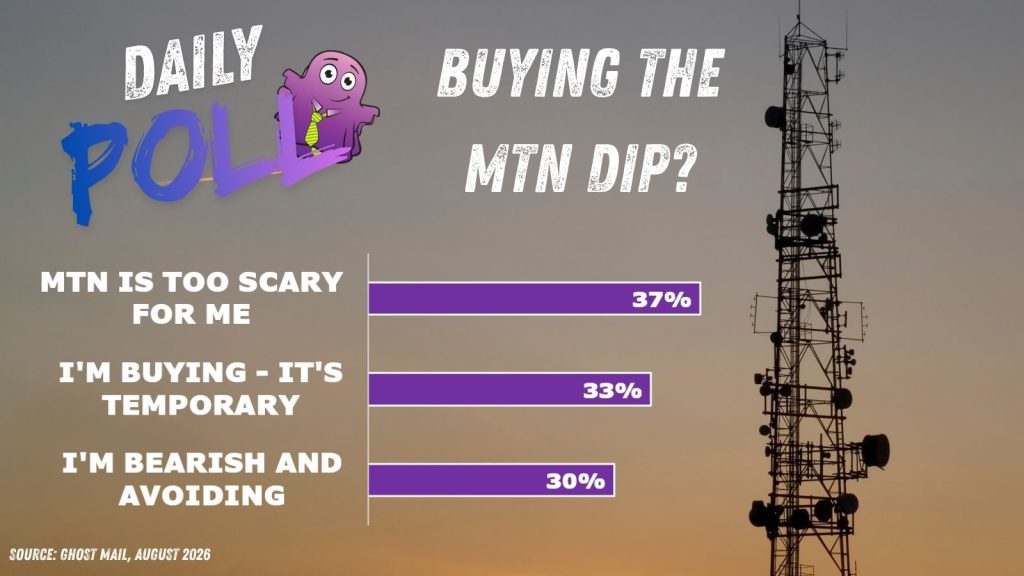
Results of MTN poll:


Nibbles:

  • Director dealings:
    • A director of Vunani (JSE: VUN) bought shares worth nearly R8.7 million in an off-market trade. The director in question is Marcel Golding, whose company Geomer Investments now has a 20.59% stake in Vunani.
    • The CEO of Marshall Monteagle (JSE: MMP) bought shares in the company worth almost R1.8 million.
    • An entity associated with the Deputy CEO of Octodec Investments (JSE: OCT) bought shares worth R73k.
  • Nigerian energy company Oando (JSE: OAO) released results for the six months to June. Average production was within guidance and operating costs were down 18% on a per-unit basis, reflecting production efficiencies. Revenue increased by 20% and profit after tax was up 8%. A substantial increase in capex was driven by upstream drilling. There’s very little liquidity in this stock.
  • Hosken Consolidated Investments (JSE: HCI) has confirmed that all conditions precedent for the Squirewood transaction with SACTWU have been fulfilled or waived. Squirewood also elected to exercise the Squirewood option, which means that SACTWU now holds only 2.25% in HCI. Squirewood is up to a 25.73% beneficial interest.
  • The boardroom battle at Trustco (JSE: TTO) continues. The company has given notice of a general meeting to be held on 18th August. Riskowitz Capital Management has requisitioned this meeting under s189 of the Namibian Companies Act. The resolutions on the table are to remove current directors and replace them with five nominees put forward by Riskowitz. The name you’ll recognise among the nominees is Grant Pattison, who previously led Massmart and Edcon. He certainly knows his way around a turnaround story.
  • When aReit (JSE: APO) listed, I really upset them by pointing out a number of flaws in their proposed valuation. But as bearish as I was, I didn’t foresee a world in which they would be unable to get audited financials right. They are still trying to get financials done for the years ending December 2023 and December 2024. There seems to be a highly technical application of IFRS here for a company that the directors describe as having four invoices per month for just four lease agreements. As I pointed out at the time of the listing, why on earth was this business model even listed in the first place? It’s been a messy situation that would’ve been avoided entirely by just staying private.

Ghost Bites (JSE Limited | Nedbank)

In this edition of Ghost Bites:

  • Corporate actions may be quiet, but JSE Limited is doing just fine
  • There’s much to learn from Nedbank’s interim numbers and their focus areas

Corporate actions may be quiet, but JSE Limited is doing just fine (JSE: JSE)

There’s much more to the owner of the JSE than people think

JSE Limited is a listed company. This always surprises market newbies.

People refer to “the JSE” as the exchange, but it’s also a listed company with a market cap of R13 billion and a 12-month share price increase of 12%. Add in the dividend and you get to a total return of over 19.5%. Clearly, they are doing well.

But how can that be? All we hear about is companies delisting from the market. Surely the JSE is going bankrupt at the speed of light?

Although losing listed companies isn’t helpful, the truth of it is that companies with very little liquidity aren’t of much value to the exchange. If they just sit there, often late on financial reporting and dealing with other issues, they just cause far more headaches than they are worth.

Another important point is that the equity market is just one part of the business model at JSE Limited. There’s a vibrant debt market for example, along with other areas like derivatives. The JSE is also required to have an enormous regulatory capital balance (currently R835 million), so the results are impacted by investment returns on that capital. It’s not just about the number of listed companies.

Here’s the proof: we certainly haven’t seen a 14.1% increase in the number of listings on the market, yet that’s the revenue growth that the company achieved for the six months to June 2026. Interesting, right?

This table shows you how diversified the business actually is:

One area where the lack of activity is being felt is in JIS, which earns revenue based on corporate actions (among other things). JIS was down 5.6%, although I suspect that the underlying corporate action revenue was down by a lot more. The corporate finance industry (where I spent several years after articles) has been forced to focus on private company transactions in recent years, as there just isn’t enough going on in the listed space.

Total expenditure grew by 11.5%, so they have achieved margin uplift (revenue growth was ahead of expenses). I must point out the 22.8% increase in personnel expenses within that number. This is something to keep an eye on, although a fair chunk of it seems to relate to “organisational redesign”. If you accept the company’s adjustment for once-off costs, then personnel expenses were up by 7.8% – a far more reasonable number.

Earnings before interest and tax (EBIT) increased by a juicy 21.4%. Below that line, net finance income actually declined by 9.8%, so that took some of the shine off.

Net profit after tax increased by 16.9% and HEPS was up by 18.8%.

Net cash from operations was up by 20.6% to R625 million, so there’s solid conversion of EBIT (R774 million) into cash. But the capex number really stands out, having ballooned from R27 million to R110 million. They don’t really give further details, noting only that they are focused on “protecting and growing the core business” – in other words, it’s a mix of sustaining and expansionary capex.

This is a strong set of interim numbers. Revenue will hopefully continue its positive trajectory in the second half of the year, as expense pressures are coming through the system. The company has revised its full year 2026 operating expenses growth to 6% – 8% (up 100 basis points vs. previous guidance). Full year capex is expected to be between R190 million and R230 million, in line with previous guidance.

Ghost Bite: JSE Limited is certainly investing heavily for growth. I’ll always want to see this translate into more listings, but the business is much broader than that.


There’s much to learn from Nedbank’s interim numbers and their focus areas (JSE: NED)

The strategy in Africa is one thing, but the South African numbers are filled with interesting nuggets

Nedbank has released results for the six months to June 2026. Before I give you my views on them, I want to thank the group for valuing the Ghost Mail audience. Nedbank has placed their results on the Ghost Mail website for your convenience. Please do check them out!

As always, what you’ll read below is my independent take on the numbers.

The green bank came into 2026 expecting a year that would be anything but green. Headline earnings were flat for the six months, with the group noting that this outperformed their expectations. I must immediately highlight that if you exclude the base effect of Ecobank, you’ll find headline earnings growth of 12%. Diluted HEPS on that basis was up 15%. That’s more like it!

Another stat I’ll quickly deal with is the credit-loss ratio, which has moved up from 81 basis points in H1 2025 to 95 basis points in H1 2026. The retail book is currently running above the through-the-cycle target range, so that’s a concerning data point for South African consumers. There’s been a particularly nasty spike in home loans and credit cards.

Just when investors in South African consumer stocks thought it couldn’t get any worse, we get a data point like this. Sigh.

Nedbank’s interim dividend per share is up by 2%, so that’s probably the fairest reflection of the underlying growth in the group at the moment. The numbers only inched upwards as Nedbank moves through a critical transition phase.

But the future is what really counts. Nedbank is making significant strategic changes to their group that will hopefully pay off in years to come. With the shares trading on a P/E multiple of roughly 7.5x, the market isn’t exactly putting a premium on the growth prospects right now. Nedbank bulls will argue that this is where the opportunity lies.

The obvious strategic change for me to mention is in Africa. Having gotten out of Ecobank, Nedbank decided to go after a controlling stake in NCBA Group. This is an East African financial services group that would give Nedbank a far more compelling presence in Africa than they’ve had before.

An argument could certainly be made that the 21% stake in Ecobank was a half-pregnant strategy, which simply doesn’t cut it vs. what competitors like Absa (JSE: ABG) and Standard Bank (JSE: SBK) have been doing on the continent. But with NCBA, the size of the prize after this deal is a controlling stake in a tier 1 bank in Kenya. That’s a whole lot more interesting.

In terms of the deal process, the NCBA offer closed on 10 July and was accepted by enough holders for Nedbank to achieve the desired 66% stake. They now need to achieve the various regulatory approvals to get the deal across the line.

But here’s the thing: even with this transaction, the pro-forma split of headline earnings would be roughly 86% from South Africa. The Africa story is becoming more interesting, but remains small overall.

In Nedbank’s home market, the recent acquisition of iKhokha is an important step into the SME market. The integration of Eqstra has given them a stronger business in fleet management. We have a very competitive market, with Nedbank trying to focus on specific growth engines.

This means we need to take a closer look at the segments.

The Corporate and Investment Banking (CIB) business, which focuses on the biggest corporates, achieved growth in advances of 8%. This part of the business tends to be driven by sector specialisation and deep relationships. For example, trade finance revenue was up by 18% thanks to flows in commodity trading and agriculture.

Deposits went up 14%, so these companies are sitting on significant cash at the moment. Non-interest revenue increased by 16%, driven by strong deal flow.

In Business and Commercial Banking (BCB), which focuses on the mid-market and SME space, advances were up 6% and deposits grew by 7%. This segment doesn’t appear to be as cash flush as the biggest corporates. Non-interest revenue increased by 14%.

In Personal and Private Banking (PPB), which is the retail banking segment, main banked clients actually increased by 2%. I think that’s pretty good when you consider the competitive bloodbath out there. On the higher income side, they grew clients in Private, Wealth and Stockbroking by 8%. Another juicy growth engine to note is insurance income, up by 21%.

With deposits up by 4%, retail deposit market share increased from 16.8% (December 2025) to 17.0% in May 2026. Their target is to be above 17%, so that’s encouraging.

This is a good opportunity to bring you a particularly interesting slide from the analyst presentation. Regulatory filings (the “BA900” reference) allow Nedbank and its competitors to accurately work out their market share across different categories. As you’ll see below, Nedbank is actually the market leader in commercial mortgages and retail vehicle finance. I must, however, note the decline in retail vehicle finance market share, something to keep an eye on given how lucrative this space is in South Africa:

Another area that I want to focus on is renewable energy financing. They have exposure of R56 billion to this asset class, with a further pipeline of R26 billion for the second half of 2026. To understand more about this space, I recently recorded a podcast with Tokollo Tau of Nedbank. Listen to it below or get the transcript here.

Overall, Nedbank expects Return on Equity (ROE) – currently at 15% – to move above 15% in 2026. Shareholders will be happy to see that direction of travel.

Ghost Bite: The medium-term goal is for ROE to reach 17%. I can tell you for sure that the additional 2 percentage points will be very hard to unlock. If Jason Quinn gets that right during his tenure as CEO, it will go down as a highly impressive stint in local banking.